
Blog Sweeping Reforms to Business Insolvency Laws Announced Today
Sweeping Reforms to Business Insolvency Laws Announced Today
Major Reform of Australian Insolvency Laws announced today: What does this mean for Your Business?
On 25 September 2020 the Australian Government announced what it called the most sweeping changes to Australian insolvency law in over 30 years. Businesses with liabilities under $1 million would be able to restructure debt on a debtor in possession basis, modelled on Chapter 11 in the United States, rather than hand control to an external administrator.
Major Reform of Australian Insolvency Laws announced today: What does this mean for Your Business?
The Morrison Government has today announced the most sweeping changes to Australian Insolvency Law in over 30 years.
In anticipation of a significant increase in the number of small businesses being put into external administration following the end of temporary measures extended until 31st December, the Australian Government has today announced major changes to come into effect 1st January 2020.
What are the changes?
The reforms will allow businesses with liabilities of less than $1 million to restructure their debt, similar to the Chapter 11 bankruptcy model in the United States.
The previous “creditor in possession” model will be replaced with the “debtor in possession” model, where businesses can restructure their debts without giving up control to appointed administrators.
Click here to read the Aust Govt. Fact Sheet released today.
What does your business need to consider in light of these changes?
Credit risk management is important in good times, in slow and uncertain times with less protection it is even more critical for businesses.
Businesses need to consider:
- How can you jump the queue for payment with customers you are worried may be insolvent?
- Should you immediately stop extending credit to customers who may be insolvent?
- Should you be running credit checks on ALL customers (good, bad, old), every time you extend credit in these extraordinary times?
- What measures do you have in place to best protect your business?
Credit risk management is all about good processes, systems, and data. But it does not need to be difficult, or time-consuming. To see how you can implement an effective system by COB today watch the demo.
Related reading
 Payday Super is live. The quarterly float is gone. What CFOs are learning about the new working capital shape. Blog · 25 Sep 2026
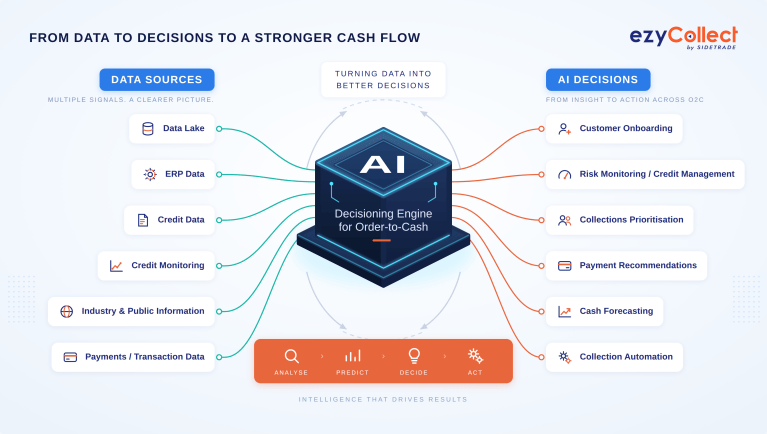 AI in Order-to-Cash: What It Actually Does for Accounts Receivable (and What’s Really Changed) Featured · 18 Sep 2026
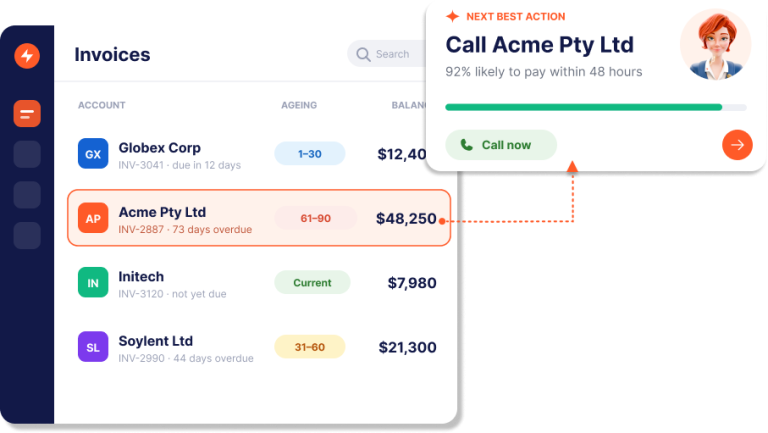 Chase Smarter. The AI trained on $8.8 trillion in B2B payments, now in your team’s corner.Blog · 12 Jun 2026